Article Headers (20)-min

FMP? - Know everything about Fixed Maturity Plan

Many of us want to invest in instruments that are not very risky and generate good risk-free returns. Here comes the concept of investing in Fixed Maturity Plans (FMPs). 

What are FMPs?

These are closed-end debt funds, sold as if they were replacements for multi-year fixed deposits. The idea was:

  • You bought a fund
  • The fund bought some debt securities scheduled to mature in a certain period say 3 years.
  • After three years, the fund gave you back the maturity amount minus their fees and all that.

FMPs invest in commercial instruments, highly rated corporate bonds, and various money market instruments. The basic rule in the FMP is to park money in an instrument that has a similar maturity date.

Features of FMPs

  1. Fixed Maturity - The maturity period of an FMP is fixed and once you have invested through NFO (new fund offering), your investment is essentially locked in till maturity. The maturity period of FMPs is usually more than 3 years from the date of unit allocation. This ensures that indexation benefits can be obtained on FMP investments. Read more about indexation and capital gains here
  2. Reduced Interest Rate Risk - FMPs are least exposed to interest rate risk, as the fund holds instruments till maturity-getting a fixed rate of return. Interest rate risk indicates that whenever there is a change in the interest rate, the value of the underlying security and hence, the NAV of the fund would change (more or less) depending on the movement of interest. Locked-In Rates: While locked-in rates are an excellent choice during a falling interest rates regime, the same can become a problem during a period of rising interest rates. When market rates move upwards, locked-in rates can lead to missed opportunities concerning potentially higher returns coupled with possibly lower risk levels. You can learn more about it here -NM 104: Basics of Mutual Funds
  3. Low Liquidity - FMPs are not liquid, you cannot withdraw before the completion of full tenure. So, if you invest in an FMP of 3-year tenure, you can withdraw only after 3 years and not in between. 
  4. Lower tax liability - A majority of new FMPs feature a maturity period of 3 years or more. This ensures that long-term capital gains tax rules including indexation benefits apply to capital gains from these non-equity investments. Indexation provides investors with the benefit of factoring in inflation, which reduces overall tax liability on gains. Read more about mutual fund taxation rules
  5. Returns Not Guaranteed: Fixed Maturity Plans provide investors with the benefit of locked-in returns from instruments held till maturity and high-quality investments minimize the credit risk for investors. That said, the low potential risk does not mean zero risks for the investors, and returns from FMPs are still market-linked. As a result, returns from FMPs are not guaranteed unlike other fixed return instruments such as fixed deposits.
  6. Not similar to fixed deposit
    Comparison Criteria Fixed Maturity Plans Fixed Deposit
    Returns Market – Linked Returns Guaranteed Returns
    Taxation Capital Gains Taxation Rules apply to the  benefit of indexation Interest is taxed as per the Income Tax slab rate of the investor
    Liquidity Low Liquidity Premature withdrawal options and sweep-in fixed deposits make it very liquid.
    Maturity Options Varies for each scheme (typically 3-4 years) Varies by a bank (typically 7 days to 10 years)
  7. Banks waive penalties

On the other hand, an increasing number of banks are not levying any penalties on premature withdrawal of fixed deposits. The State Bank of India, for instance, does not charge any penalty on premature withdrawals from short-term deposits of Rs 15 lakh and above after seven days.

In cases of tenure of more than one year, there is a small penalty. The deposit earns 0.5% below the rate applicable for the period the money remained with the bank or 0.5% below the contracted rate, whichever is lower.

This makes bank FDs a better proposition for those in the lower tax brackets. The tax on FMPs will only be marginally lower and not make a significant difference for someone who earns less than Rs 5 lakh a year. Even though the tax will be higher on FDs, they will offer greater liquidity to the investor.

What are the things you must check before investing in an FMP?

While FMP offers several advantages over other fixed-income products, there are still certain factors that investors should keep in mind before taking the plunge. Here are a few of them.

  • Check Indicative portfolio:  If the indicative portfolio shows the portfolio will invest the majority of the corpus in bank certificates of deposits (CDs), then the portfolio may have lower risks compared to FMP’s which invest predominantly in Commercial Papers (CPs). Seen from the other side, having Commercial Papers in the portfolio may mean slightly higher rates. So as an investor before investing in an FMP you should have a clear idea about the risks you are willing to take and how does the portfolio looks like.
  • Credit rating of the securities:  You should also check the scheme’s offer document for the minimum credit rating of the securities the fund intends to invest in. The investors should also note that the higher the credit ratings of their securities, the lower the returns would be for the FMPs and vice versa. However, lower credit rating securities have higher credit risks; hence investors should keep in mind the same. Credit risk indicates the risk of default. 
  • Expense Ratio of the scheme – Investors should select a scheme that has a reasonable expense ratio as per the tenor of the FMP, as a higher expense ratio reduces the overall yield on the FMP.
  • Maturity of the Scheme: Some of the FMPs launched between January and March every year offer double-indexation benefits. Double Indexation helps reducing long term capital gains thereby reducing overall tax liability

TAXATION OF FMPS

As FMPs are a type of debt fund, they are taxed like other debt funds. Investments held for more than 36-months are taxed at the rate of 20%. But there is an indexation benefit available here. With indexation, you get to increase the purchase price of FMP units in accordance with the inflation during the period. This helps in reducing your taxable returns from FMPs. Do note that tax-saving FDs falling under 80C do not allow premature withdrawal. Where FMPs score over FDs is indexation benefit, which results in paying lower taxes.


Who Should Consider Fixed Maturity Plans?

Investors who are looking for higher returns in comparison to FDs and RDs and are willing to accept frequent market fluctuations can invest in FMP’s. Additionally, investors must be willing to lock in their funds for a time period of 3 years. In a bid to provide higher income to their investors, FMPs invest in instruments that bear some credit risk so ensure that you understand the risk when you invest in FMPs and do not invest in them as a replacement for fixed deposits.

Separately, for all your emergency funds - we would advise you to continue to invest in fixed deposits or liquid mutual funds. For short-term goals of up to 3 years - you can invest in short-term debt funds or could consider FMPs. But do remember that FMPs come with Fixed Tenure and hence, you cannot access it unless the tenure is completed.


Consult your financial advisor to understand how these funds fit into your risk appetite and goals. We are SEBI registered investment advisors and can help you make sound investment decisions - you can reach out to us at iplan@wealthcafe.in, in order to help you make a financial plan for yourself.

To learn more about Asset classes enroll in our course NM 103: Basics of Asset Classes

You can also check our course on Mutual Funds NM 104: Basics of Mutual Funds
When to exit from Mutual Funds or stop SIP?

One of the most common themes of discussion about Mutual Funds is – When it is a good time to invest? While answers to this question are readily available, a relatively less discussed theme is – When is a good time to exit your Mutual Fund investments? 

If you have been paying those SIP installments over a period of time, chances are that at some point, you would have asked yourself whether you should discontinue the payments.

So what are the triggers that should prompt you to exit from mutual funds or stop your SIP? In this blog, we will discuss specific instances of when you should consider exiting from your Mutual Fund investments and also how to come up with a viable exit strategy that works for you. 

Things To Know Before You Exit the Fund

It’s essential to choose your alternatives before you exit a fund. You need to ensure that the new fund is in sync with your needs. For instance, if you had invested in large-cap funds because they are less risky and find that your fund has now been merged with a mid-cap fund, then you can redeem the combined fund for a fund composed of pure large-cap units only.

Along with this, you also need to take the LTCG (Long-Term Capital Gains) tax into account and see to it that the exit and redemption do not cause you huge losses.

Know when to exit from investments in mutual funds

Sometimes even during your goal period, there might be instances demanding you to exit from investments. In such scenarios, exiting the investment is suggested only when:

  • When you achieve your financial goal

The basic reason you invest is to achieve your goals and if your goals are achieved or are at the stage where you need the money for the goal, you exit the fund. It is very simple right. However, your debt: equity allocation would tell a different story. If you had invested in a long-term goal say your kid's education of 15 years then you start exiting equity in the 12th year when it becomes a short-term goal and switch your money to liquid debt funds (safer options). From this debt fund, you redeem your units as and when you need money for the goal. Now after the 12th year you are sure that you will have money whenever you will need it for your child’s education. You no longer have to continue to invest after the 15th year. This is the most important reason or timing to exit the fund.

  • Consistent poor performance of the fund

If a scheme has underperformed consistently versus its category peers over the past several quarters, you should consider exiting the scheme in favor of a more consistent performer. There can be many reasons behind your fund’s dipping performance.

It might have taken exposure to an unsuitable sector or theme at an inappropriate time. In yet another case, your debt fund might have invested in low-credit-rated securities and failed to earn high returns as planned. 

Therefore, in order to gain the benefits, the mutual fund's investments should be tracked regularly. The performance of the mutual funds has to be seen in the right way. Following are some of the measures:-

  1. Compare your fund with the benchmark index
  2. Compare with the category average
  • Fund level changes are making you uncomfortable

This is quite a common problem. For example, the fund manager who was doing a wonderful job for the last 10 years may have moved on. Occasionally, the AMC gets sold to a new fund manager and you may be uncomfortable with the strategies of the fund. There are also occasions when the fund may have made some changes to the objectives of the fund or its asset mix which may be incongruent with your goals. These are again genuine cases for you to terminate your SIP or exit from the particular scheme. You can look for other funds that are consistent with your objectives.  

  • To Rebalance Your Investment Portfolio

Rebalancing and asset allocation are crucial parts of your investment strategy. 90% of your returns are determined from your rebalancing rather than the exact fund you invested in. For instance, when you started investing your asset allocation was 70:30 into equity and debt. After completion of one year, your target allocations might have skewed. It might be the result of the recent rally increasing NAV of the equity component of the portfolio.

Or, in another case, a macroeconomic policy shift may have made large-cap stocks more favorable over others. All of these would trigger a portfolio rebalancing. In this, you sell those funds which have become irrelevant in the current context. You invest that money in other funds which look more favorable. 

Ideally, SIPs should be investments in perpetuity. However, like all investments, one must review, re-balance and reset portfolios in line with current requirements and their risk appetite (which are always changing)

  • The fund is all over the media for the wrong reasons

Let us start with a caveat here! Not everything that appears on the media or social media needs to be entirely believed. They must be taken with a pinch of salt. But when you see consistent negative cues like SEBI investigations, penalties imposed, customer dissatisfaction, services issues, allegations of circular trading, etc, there is obvious room for worry. Random media reports are understandable. However, do your own research that if you find such news temporary and you have the risk of holding on, you could consider not selling. Just the media news cannot be a reason, otherwise, you will be changing your portfolio every 6 months.

  • There is an emergency

In case of financial emergencies, when your emergency fund isn’t sufficient to meet your requirement, you need to consider exiting your mutual fund investments. Therefore, funds should be parked in liquid funds for contingencies like emergencies.


If not for the above reasons, holding your investments for longer durations is always suggested. Along with an investment plan, always have an exit strategy ready for your investments. 


Always remember why you invested in a particular fund (and please may that not be ‘best funds of 2020’). Once you map your investments to your goals, these questions will not be very difficult for you to answer. As you exit when your goals are due or only when something gravely is wrong with the fund. Otherwise, it is Janam Janam ka Saath (especially in equity funds).


Hence, we always recommend learning about goal setting and investing properly to achieve your goals - check our course- NM 104: Basics of Mutual Funds
Income-tax Rates FY 2021-22 (AY 2022-23)

Before knowing the tax rates, it is very important to understand the terms Financial year (FY) and Assessment Year (AY).

The below-mentioned tax rates/ slab is on the income earned for the period 1 April 2021 to 31 March 2022. FY stands for the ‘financial year’ which is from 1 April 2021 to 31 March 2022. AY stands for Assessment year which is 1 April 2022 to 31 March 23.

For individuals, the due date to file the income tax return for the income earned from 1 April 2021 to 31 March 2022 is 31 July 2022. 

Income tax Rates 

  1. Income Tax Rate & Slab for Individuals & HUF:
    1. Individual (Resident or Resident but not Ordinarily Resident or non-resident), who is of the age of less than 60 years on the last day of the relevant previous year & for HUF:


Taxable income Tax Rate

(Existing Scheme)

Tax Rate

(New Scheme)

Up to Rs. 2,50,000 NIL NIL
Rs. 2,50,001 to Rs. 5,00,000 5%  5% 
Rs. 5,00,001 to Rs. 7,50,000 20% 20%
Rs. 7,50,001 to Rs. 10,00,000 20% 15%
Rs. 10,00,001 to Rs. 12,50,000 30% 20%
Rs. 12,50,001 to Rs. 15,00,000 30% 25%
Above Rs. 15,00,000 30% 30%


  1. Resident or Resident but not Ordinarily Resident senior citizen, i.e., every individual, being a resident or Resident but not Ordinarily Resident in India, who is of the age of 60 years or more but less than 80 years at any time during the previous year:
Taxable income Tax Rate

(Existing Scheme)

Tax Rate

(New Scheme)

Up to Rs. 2,50,000 Nil Nil
Rs. 2,50,001 to Rs. 3,00,000 Nil 5%
Rs. 3,00,001 to Rs. 5,00,000 5% 5%
Rs. 5,00,001 to Rs. 7,50,000 20%  10%
Rs. 7,50,001 to Rs. 10,00,000 20%  15%
Rs. 10,00,001 to Rs. 12,50,000 30%  20%
Rs. 12,50,001 to Rs. 15,00,000 30%  25%
Above Rs. 15,00,000 30%  30%


  1. Resident or Resident but not Ordinarily Resident super senior citizen, i.e., every individual, being a resident or Resident but not Ordinarily Resident in India, who is of the age of 80 years or more at any time during the previous year:


Taxable income Tax Rate

(Existing Scheme)

Tax Rate

(New Scheme)

Up to Rs. 2,50,000 Nil NIL
Rs. 2,50,001 to Rs. 5,00,000 Nil 5%
Rs. 5,00,001 to Rs. 7,50,000 20% 10%
Rs. 7,50,001 to Rs. 10,00,000 20% 15%
Rs. 10,00,001 to Rs. 12,50,000 30% 20%
Rs. 12,50,001 to Rs. 15,00,000 30% 25%
Above Rs. 15,00,000 30% 30%


  1. Surcharge:
    a) 10% of Income-tax where total income exceeds Rs.50 lakh
    b) 15% of Income-tax where total income exceeds Rs.1 crore
    c) 25% of Income-tax where total income exceeds Rs.2 crore
    d) 37% of Income-tax where total income exceeds Rs.5 crore
  2. Note: The enhanced surcharge of 25% & 37%, as the case may be, is not levied, from income chargeable to tax under sections 111A, 112A, and 115AD. Hence, the maximum rate of surcharge on tax payable on such incomes shall be 15%.
  3. Education cess:4% of income tax plus surcharge
  4. Note: A resident or Resident but not Ordinarily Resident individual is entitled to a rebate under section 87A if his total income does not exceed Rs. 5, 00,000. The amount of rebate shall be 100% of income tax or Rs. 12,500, whichever is less. rebate under section 87A is available in both schemes I.e. existing scheme as well as the new scheme.


  1. Income Tax Rates for AOP/BOI/Any other Artificial Juridical Person:
Taxable income Tax Rate
Up to Rs. 2,50,000 Nil
Rs. 2,50,001 to Rs. 5,00,000 5%
Rs. 5,00,001 to Rs. 10,00,000 20%
Above Rs. 10,00,000 30%


Surcharge:

  1. a) 10% of Income-tax where total income exceeds Rs.50 lakh
  2. b) 15% of Income-tax where total income exceeds Rs.1 crore
  3. c) 25% of Income-tax where total income exceeds Rs.2 crore
  4. d) 37% of Income-tax where total income exceeds Rs.5 crore

Note: Enhanced Surcharge rate (25% or 37%) is not applicable in case of specified incomes I.e. short-term capital gain u/s 111A, long-term capital gain u/s 112A & short-term or long-term capital gain u/s 115AD(1)(b).

Education cess: 4% of tax plus surcharge


  1. Tax Rate for Partnership Firm:

A partnership firm (including LLP) is taxable at 30%.

Surcharge: 12% of Income-tax where total income exceeds Rs. 1 crore

Education cess: 4% of Income-tax plus surcharge


  1. Income Tax Slab Rate for Local Authority:

A local authority is Income taxable at 30%.

Surcharge: 12% of Income-tax where total income exceeds Rs. 1 crore

Education cess: 4% of tax plus surcharge


  1. Tax Slab Rate for Domestic Company:

A domestic company is taxable at 30%. However, the tax rate is 25% if turnover or gross receipt of the company does not exceed Rs. 400 crore in the previous year.

Particulars Tax Rate(%)
If turnover or gross receipt of the company does not exceed Rs. 400 crore in the previous year 2019-20 25%
If the company opted section 115BA (Note 1) 25%
If the company opted for section 115BAA (Note 2) 22%
If the company opted for section 115BAB (Note 3) 15%
Any other domestic company 30%


Note 1: Section 115BA – A domestic company which is registered on or after March 1, 2016, and engaged in the business of manufacture or production of any article or thing and research in relation to (or distribution of) such article or thing manufactured or produced by it and also It is not claiming any deduction u/s 10AA, 32AC, 32AD, 33AB, 33ABA, 35(1)(ii)/(iia)/(iii)/35(2AA)/(2AB), 35AC, 35AD, 35CCC, 35CCD, section 80H to 80TT (Other than 80JJAA) or additional depreciation, can opt section 115BA on or before the due date of return by filing Form 10-IB online. The company cannot claim any brought forward losses (if such loss is related to the deductions specified in the above point).

Note 2: Section 115BAA – Total income of a company is taxable at the rate of 22% (from A.Y 2020-21) if the following conditions are satisfied:

– Company is not claiming any deduction u/s 10AA or 32(1)(iia) or 32AD or 33AB or 33ABA or 35(1)(ii)/(iia)/(iii)/35(2AA)/(2AB) or 35AD or 35CCC or 35CCD or section 80H to 80TT (Other than 80JJAA).

– Company is not claiming any brought forward losses (if such loss is related to the deductions specified in the above point).

– Provisions of MAT are not applicable to such companies after exercising of option. The company cannot claim the MAT credit (if any is available at the time of exercising section 115BAA).

Note 3: Section 115BAB – Total income of a company is taxable at the rate of 15% (from A.Y 2020-21) if the following conditions are satisfied:

– Company (not covered in section 115BA and 115BAA) is registered on or after October 1, 2019, and commenced manufacturing on or before 31st March 2023.

– Company is not formed by splitting up or reconstructing a business already in existence.

– Company does not use any machinery or plant previously used for any purpose.

– Company does not use any building previously used as a hotel or a convention center, as the case may be.

– Company is not engaged in any business other than the business of manufacture or production of any article or thing and research in relation to (or distribution of) such article or thing manufactured or produced by it. Business of manufacture or production shall not include the business of –

  • Development of computer software;
  • Mining ;
  • Conversion of marble blocks or similar items into slabs;
  • Bottling of gas into the cylinder;
  • Printing of books or production of the cinematographic film; or
  • Any other notified by Central Govt.

– Company is not claiming any deduction u/s 10AA or 32(1)(iia) or 32AD or 33AB or 33ABA or 35(1)(ii)/(iia)/(iii)/35(2AA)/(2AB) or 35AD or 35CCC or 35CCD or section 80H to 80TT (Other than 80JJAA and 80M).

– Company is not claiming any brought forward losses (if such loss is related to the deductions specified in the above point).

– Provisions of MAT are not applicable to such companies after exercising of option. The company cannot claim the MAT credit (if any available at the time of exercising of section 115BAA).

Surcharge:

  1. a) 7% of Income-tax where total income exceeds Rs.1 crore
  2. b) 12% of Income-tax where total income exceeds Rs.10 crore
  3. c) 10% of income tax where domestic company opted for section 115BAA and 115BAB

Education cess: 4% of Income-tax plus surcharge.


  1. Tax Rates for Foreign Company:

A foreign company is taxable at 40%

Surcharge: 

  1. a) 2% of Income-tax where total income exceeds Rs. 1 crore
  2. b) 5% of Income-tax where total income exceeds Rs. 10 crore

Education cess: 4% of Income-tax plus surcharge.

  1. Income Tax Slab for Co-operative Society
Taxable income Tax Rate

(Existing Scheme)

Tax Rate

(New Scheme)

Up to Rs. 10,000 10% –
Rs. 10,001 to Rs. 20,000 20% 22%
Above Rs. 20,000 30% –


Surcharge:

  1. a) 12% of Income-tax where total income exceeds Rs. 1 crore
  2. b) In the case of Concessional scheme, the surcharge rate is 10%

Education cess: 4% of Income-tax plus surcharge.

Disclaimer: – The articles are for information purposes only. Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. You must consult a financial advisor who understands your specific circumstances and situation before taking an investment decision.

Things you must know about the new income tax portal for easy filing of the return for FY 21-22.

Income Tax Return ITR E-Filing Direct Link

  1. There is a direct link for the e-filing of Income Tax returns. It is the official portal of Income Tax India.
  2. You need to visit – www.incometaxindiaefiling.gov.in to file your income tax return.
  3. Taxpayers can file ITR, verify income tax returns, link Aadhaar with PAN, know Aadhaar-PAN link status, e-pay tax, track status of e-filed Income Tax Return status, know tax deductors across India etc.

Here are key things to know about filing ITR:


What are the new options for filing ITR on the new portal?

The I-T department has encouraged taxpayers to update their profiles to avail accurate pre-filled ITRs and enhanced user experience.

On the top of the new website, one can find the tab to access individual-based help content. Clicking on the application tab takes an individual to view guidance on how to file ITRs and applicable forms for the same. Deductions, refund status, tax slab and other related information are also present there.

The department has claimed that the new IT return e-filing portal and the new mobile app will be easy to use for taxpayers.


What are the additional features of the new portal in terms of ITR filing?

The new portal has a drop-down menu for taxpayers for checking instructions on ITR filing, refund status, and tax slabs. The new site also has detailed user manuals, FAQs and videos to help taxpayers understand various services available on the portal.


What are the forms of return prescribed under the income tax law?

The Income Tax Department has notified 7 forms for filing ITR this year. These forms include Sahaj (ITR-1), Form ITR-2, Form ITR-3, Form Sugam (ITR-4), Form ITR-5, Form ITR-6 and Form ITR-7.


What are the different modes of filing the return of income?

The return form can be filed with the Income-tax Department in any of the following ways, -

(i) by furnishing the return in a paper form;

(ii) by furnishing the return electronically under digital signature;

(iii) by transmitting the data in the return electronically under electronic verification code;

(iv) by transmitting the data in the return electronically and thereafter submitting the verification of the return in Return Form ITR-V;


How to file the return of income electronically?

The Income-tax Department has established an independent portal for e-filing of return of income. The taxpayers can log on to https://www.incometax.gov.in for e-filing the return of income.


What are the benefits of filing my return of income?

Filing of return earns an individual the dignity of consciously contributing to the development of the nation. Apart from this, income tax returns validate an individual's credit-worthiness before financial institutions and make it possible for him/her to access many financial benefits such as bank credits, etc.

What is loss aversion bias in investing?

Loss aversion is a tendency in behavioral finance where investors are so fearful of losses that they focus on trying to avoid a loss more so than on making gains. The more one experiences losses, the more likely they are to become prone to loss aversion.

For instance, say you bought 100 shares of Yes Bank at Rs 50 per share. If the stock fell to Rs 30, and you bought another 100 shares, your average price per share would be Rs 40.  If the stock further fell to Rs 15, and you bought another 100 shares, your average price per share would be Rs 30. And if you now feel the need to sell, you would be facing a loss of approx 53%. (We have taken this only for an example purpose, no recommendation or fundamental is done for the stock)

Purchasing more shares to average down the price wouldn't change that fact, so do not misinterpret averaging down as a means to magically decrease your loss. This is a very common practice followed by investors where they keep buying more shares at the dip, thinking they are lowering their cost, without understanding that they are just incurring more losses. Such methods of buying at a lower cost must be followed only and only where the company has strong fundamentals and you are sure that the current dip in the price is due to some change in the market scenario. If the losses continue, then do you think buying more is the solution or booking your losses is?

Research on loss aversion shows that investors feel the pain of a loss more than twice as strong as they feel the enjoyment of making a profit.

EXAMPLES OF LOSS AVERSION

Below is a list of loss aversion examples that investors often fall into:

  • Investing in low-return, guaranteed investments over more promising investments that carry a higher risk
  • Not selling a stock that you hold when your current rational analysis of the stock clearly indicates that it should be abandoned as an investment
  • Selling a stock that has gone up slightly in price just to realize a gain of any amount, when your analysis indicates that the stock should be held longer for a much larger profit
  • Telling oneself that an investment is not a loss until it’s realized (i.e., when the investment is sold)

HARMFUL EFFECTS OF LOSS AVERSION

  • Loss aversion causes investors to hold on to loss-making stocks or funds for a very long period. They refuse to sell a stock or fund at a loss and can hold on to it for long periods of time even if there are better alternative investment options available.
  • Aversion for losses makes investors hold on to loss-making stocks or funds till the loss is recovered. Ultimately, when the investor sells the stock or fund, a long time may have elapsed and the return on the investment is very low.
  • There are also instances of investors holding on to loss-making stocks/funds and then finally selling them at a much bigger loss than what they would have incurred if they sold earlier.
  • Loss aversion is commonly seen in property / real estate investments. Investors refuse to sell their property at a loss and hold on to it hoping the investment will turn profitable someday. Throughout the holding period of the investment, they pay interest on their loans which could have been avoided if they sold earlier.

RATIONAL STRATEGIES FOR AVOIDING LOSSES
Let’s look at some examples of how a company or an individual can reasonably minimize risk exposure and losses:

  • Hedge an existing investment by making a second investment that’s inversely correlated to the first investment
  • Invest in endowment plans/debt products that have a guaranteed rate of return so you have your safety net in place
  • Invest in government bonds directly or via mutual funds (but be aware of the liquidity and the interest rate risk over there)
  • Purchase investments with relatively low price volatility and only after thorough research. Do not just buy because something is priced low. Understand the value of it before investing.
  • Consciously remain aware of loss aversion as a potential weakness in your investing decisions and make more conscious smart decisions.
  • Invest in companies that have an extremely strong balance sheet and cash flow generation. (In other words, perform due diligence and only make investments that rational analysis indicates have genuine potential to significantly increase in value.) and DO NOT MAKE INVESTMENTS BASED ON TRENDING TWEETS AND TELEGRAM GROUPS.

CONCLUSION
No one likes to make a loss, but loss aversion can cause you to lose more money or make less money than what you feared to lose. Sometimes, it is better to book a loss and move on to alternative investment options. This moving on will help you invest for the long term better and make money eventually. 

It is difficult to separate emotions from investing, but successful investors are able to do it. You should do what is right to meet your financial goals including selling funds that are underperforming consistently and switching to better funds. A good financial advisor can help you overcome this behavioral bias. You should have a rational and objective portfolio performance evaluation process; take the help of a financial advisor if required. We are SEBI registered investment advisors and can help you make sound investment decisions - you can reach out to us at iplan@wealthcafe.in, in order to help you make a financial plan for yourself.

Taxation of Mutual Funds for FY 2021-22 (AY 2022-23).

First, let us understand what are the factors that determine Mutual Fund Taxation. The three major parts of these are below.

  • Your Residential Status-Resident or Non-Resident (NRI)

Your tax will be based on your residential status. If you are a resident then the taxation rules will be different and if NRI then it differs. Hence, first, you have to make sure of your residential status.

  • Types of Funds-Equity Funds or Non-Equity Funds-

Any fund which invests 65% or more in equity is called an Equity Fund. For example, large-cap funds, multi-cap funds, small and mid-cap funds, or equity-oriented balanced funds (where the equity exposure is 65% or more) are all called equity-oriented funds.

If the equity portion is less than that, then they are all treated as debt funds or non-equity funds. For example liquid funds, ultra-short-term funds, short-term funds, income funds, gilt funds, debt-oriented balanced funds, gold funds, funds of funds or money market funds.

  • Holding periods of Investment–

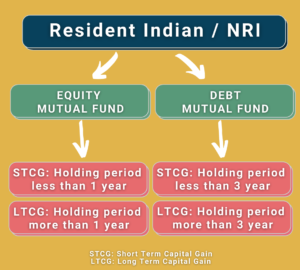
The holding period for Equity and Debt Funds will be different for taxation purposes. For equity funds, if the holding period is more than a year, then it is called the long term. If the holding period is less than a year, then such an equity mutual funds holding period is considered a short term. Whereas in

Whereas in the case of debt funds, a holding period of more than 3 years is considered as long-term. If the holding period of debt funds is less than 3 years, then it is considered short-term and taxed accordingly.

I will try to explain the same from the chart below.

The Capital Gain Mutual Fund Taxation FY 2021-22 / AY 2022-23 will be as per the below table.

Individuals

NRI

Stocks & equity oriented Mutual Funds

LTCG 10% above Rs 1 lakh gain 10% above Rs 1 lakh gain
STCG 15% 15%

Other than Stocks & equity oriented Mutual Funds

LTCG 20% with indexation Listed 20% (with indexation) & unlisted 10% (without indexation).
STCG Based on individual slabs Based on individual slabs


There is no change in Capital Gain Tax Rates from last year. Hence, the old rates will be applicable for FY 2021-22 also.

Note-Surcharge @ 15%, is applicable where the income of Individual/HUF unit holders exceeds Rs. 1 crore. Also, surcharge @10% to be levied in case of individual/ HUF unitholders where the income of such unitholders exceeds Rs.50 lakhs but does not exceed Rs.1 Cr. Further, Health and Education Cess @ 4% will continue to apply on the aggregate of tax and surcharge.

As you may be aware that during Budget 2018, LTCG was introduced again to Equity Funds. Hence, let me explain the same on how to calculate the LTCG on Equity Funds as below.

How to calculate LTCG on tax slabs & Equity Mutual Fund?

LTCG & STCG on Stocks & Mutual Funds (up to 31st January 2018)

Bought before 31st January 2018 10,000 stocks at INR 100
Sold within 365 days 10,000 stocks at INR 130
STCG Profit INR 130 15% STCG = INR 45,000
Sold after 365 days 10,000 stocks at INR 150
LTCG Higher of a) or b)

a)Actual cost (i.e INR 100)

b)Lower of the below

-The highest price of 31st Jan 2018 (Rs 120)

-Actual selling price (INR 150)

(Assumed that the highest price on 31st Jan 2018 is INR 120)

10% LTCG on INR 1,20,000

(10,000*Rs 120) - INR 1,00,000

INR 20,000

LTCG & STCG on Stocks &  Mutual Funds(from 1st February 2018)

Buy on 1st February 2018 10,000 stocks at INR 100
Sold within 365 days 10,000 stocks at INR 130
STCG Profit INR 3,00,000 5% STCG = INR 45,000
Sold after 365 days 10,000 stocks at INR 50
LTCG Profit INR 5,00,000 LTCG = Actual profit- INR 1,00,000

=INR 4,00,000

10% LTCG on INR 4,00,000 

=INR 40,000

Mutual Fund Taxation FY 2020-21 – Dividend Distribution Tax (DDT)

As I pointed above, effective from FY 2020-21, DDT was abolished in the hands of Mutual Fund Companies. Hence, any dividend you receive will be taxable for you as per your tax slab.

At the same time, if your such dividend income is more than Rs.5,000 in a Financial year, then there will be a TDS @ 10%.


Mutual Fund Taxation FY 2021-22: DDT Rates

Individual

NRI’s

Equity Oriented Schemes

As per the Tax slab As per the Tax Slab
Debt Oriented Schemes As per the Tax slab

As per the Tax slab


Security Transaction Tax (STT) for FY 2021-22

Security Transaction Charges or STT is the charges or tax when you buy or sell securities (excluding commodities and currency) through a recognized stock exchange. Therefore,

The definition of securities involves the below products.

  • Shares, scrips, stocks, bonds, debentures, debenture stock or other marketable securities of a like nature in or of any incorporated company or other body corporate;
  • Derivatives;
  • units or any other instrument issued by any collective investment scheme to the investors in such schemes;
  • Security receipt as defined in section 2(zg) of the Securitization and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002;
  • Government securities of equity nature;
  • Rights or interest in securities;
  • Equity-oriented mutual funds

Therefore, whenever you buy and sell these securities through a recognized stock exchange, then you have to pay this STT.

Now let us understand the latest Security Transaction Tax (STT) applicable for FY 2021-22.

Security Transaction Tax (STT) Rates for FY-2021-22

Transaction Type Rates

Payable By

Purchase/ of equity shares (delivery Based) 0.1% Purchaser/ Seller
Purchase of units of equity-oriented mutual fund NIL Purchaser
Sale of units of equity-oriented Mutual fund 

(delivery Base)

0.001% Seller
Sale of equity shares, units of business trust, units of equity-oriented mutual fund 

(Non-Delivery Based)

0.025% Seller
Sale of an option in securities 0.05% Seller
Sale of an option in securities, where the option is exercised 0.125% Purchaser
Sale of future in securities 0.01% Seller
Sale of units of an equity-oriented fund to the mutual fund 0.001% Seller

Sale of unlisted equity shares & units of business trust under an initial offer

0.2%

Seller


TDS (Tax Deducted at Source) Rates for NRI Mutual Fund Investors 2021-22

Below are the applicable TDS rates for NRI Mutual Fund investors for FY 2021-22.

STCG Equity-The current TDS of 11.25% which was modified from 14th May 2020 to 31st March 2021 will I think continue for STCG-Equity Funds

STCG Other than Equity-The current TDS of 22.5% which was modified from 14th May 2020 to 31st March 2021 will I think continue for STCG-Other than equity.

LTCG Equity-The current TDS of 7.5% which was modified from 14th May 2020 to 31st March 2021 will I think continue for STCG-Equity Funds.

LTCG Other than Equity-The current TDS of 15% (for listed) and 7.5% (for unlisted) which was modified from 14th May 2020 to 31st March 2021 will I think continue for STCG-Other than equity.


Wealth Café Note: You pay taxes in a Mutual fund only when the gains are realized i.e. you redeem the funds and the proceeds of the same are credited to you. Now if there is a gain then the same is taxed as the taxation of mutual funds.

Hope now you got the clarity related to Mutual Fund Taxation FY 2021-22 / AY 2022-23.

Article Headers (10)-min

What is information bias in investing?

Information bias is the tendency to evaluate information even when it is useless in understanding a problem or issue. Today, investors had much more information than before, however, is it all good information? Can this be used to make smart money decisions?

Through social media, we are now being bombarded with new information almost every hour and sometimes every few minutes. Are you one of those who feel research means checking reels on top 3 funds to buy? Checking Youtube videos to confirm your understanding of various investments? Following twitter handles or paying 199 per month for telegram groups to know what is the next multi-bagger? Social media stalking is not detailed research that provides you all the information you need to make a smart investment decision. 

Where you are following people online who agree with your viewpoints and speak the things you believe in - you are already following an information bias. 

INFORMATION BIAS IN INVESTING
You should ask yourself if some of the information you are getting is relevant at all. Information like daily NAV movement, 52 weeks high or low NAVs, best performing funds of the month, etc. is useless in our view. Should you buy or sell a fund based on its last 7 days or 30 days' performance? However, with interesting captions, they are made to look as if it is very important information that you should pay attention to. But mostly they are irrelevant but excites you into buying a particular fund purely on its return number or performance of the past few months. In many instances, investors will make investment decisions to buy or sell an investment on the basis of short-term movements in the share price. 

Likewise, for mutual fund investors, top stocks bought or sold by fund managers every month is mostly not relevant. When you are investing in mutual funds, you rely on professional fund managers to do the stock selection because you do not have their expertise or experience. Top stocks bought or sold by fund managers can be an interesting article on the internet but should you invest in Direct Equity shares based on what a Mutual Fund manager is buying or selling?

The input of information has increased tremendously, now we have people dancing and explaining financial concepts on the net where capturing that information is easy and fun, we may miss out on the crux of the whole thing when learning about finance i..e it is very personal to you. You need to understand what works for your risk profile and your goals before investing in purely basis blogs/videos and others.

HOW TO AVOID INFORMATION BIAS

  • Financial planning: Financial planning with clearly defined financial goals and investment plans to achieve different goals can help you avoid information bias. Make sure that you are committed to your financial plan.
  • Know the fundamentals of investing: Know what is important and what is not. You need to understand what will make your financial goals successful and filter out the unimportant information.
  • Do not track your portfolio on a daily basis: It is important to monitor your portfolio regularly, but you do not need to track it on a daily basis. Short-term price movements have no impact on long-term portfolio returns. If you track your portfolio on a daily basis, then you are likely to be prone to information biases. Remember why you invested and for what goals. You must invest in equity for the long term - so checking it every day is not going to help get higher returns.
  • Seek counsel before you react to information: Information that you get every day or every hour usually has no bearing on long-term portfolio performance. If you want, you can seek more information about investments, but seek the guidance of a financial advisor before you act on the information you have. We are SEBI registered investment advisors and can help you make sound investment decisions - you can reach out to us at iplan@wealthcafe.in, in order to help you make a financial plan for yourself. A lot of information you get daily may be totally irrelevant and can harm your financial interests, if you act on it without considering other factors.

Common Retirement Planning Mistakes

Retirement planning used to be a lot easier. You worked your whole life for the same company and retired at age 65 with a gold watch and a company pension.

Today it’s more complicated. Most people will change employers many times over the course of their career or work for themselves at some point. At the same time, life expectancy is increasing. On one hand, that means more retirement years to enjoy. But the flip side is that you also have more retirement years to fund.

Living a retired life without enough savings can really be a dreadful experience. If you and your spouse don’t want to be a burden on your children after retirement, it is best to start retirement planning early and stick to the retirement plan by all means.

Don’t make the mistake of relying on others – even if they are your own children – to take care of you when you have reached your twilight years. Why should you rely on others post-retirement when you lived all your life on your own terms?

To live a comfortable retirement life on your own terms, you need proper retirement planning and to achieve that you need to avoid these common mistakes.

IGNORING PRICE RISE
Inflation is a demon that comes down hard on anyone who ignores it. "Since retirement is a long-term goal, it is important to understand the impact of inflation on your financial goal
If you ignored inflation while doing the maths, revisit the numbers. Always take the real rate of return (rate of return minus inflation) while doing the calculation. Also, use a realistic rate of inflation. You can take an average of the past few years. Lastly, don't underestimate inflation. It's better to err on the side of caution.
The only investment that will help you beat inflation and still make a corpus is equity. So you need a part of it in your portfolio. You can not plan for your retirement 20 years away by parking money in FDs only. However, EPF is a great debt portion of your retirement corpus mix.

CASHING OUT EPF MONEY
Many people withdraw money from their provident fund account. This is wrong as instruments such as the Employee Provident Fund (EPF) have been designed to provide financial security after retirement. These are highly useful for retirement planning, especially due to their tax-free status.
It is not good to withdraw money from the EPF, even if it is to make a big-ticket purchase such as a house. Instead, it is better to dip into other savings; EPF should be only for post-retirement years.
Basic of Employee Provident Fund (EPF)
Lesser known facts about Employee Provident Fund (EPF)
Step by Step Process for EPF withdrawal
What Should You Do With Your Old Inactive EPF Account?
When can you withdraw your EPF?

DELAYING HEALTH INSURANCE
Medical expenses rise as a person ages. Many people don't buy individual health plans during their working life as they are covered by employers. This is not advisable as most employers give the cover only till you are employed with them.
You also have the option of porting the employer's policy to individual cover at retirement. But do not depend on group policies after retirement as employers keep changing insurers and so you may miss out on benefits accumulated in the earlier policy such as waiver of waiting period for pre-existing diseases.
It is good to buy an individual health policy early in life. It is not only cheaper but also helps you cover pre-existing illnesses after completion of the waiting period. Moreover, it covers you even after you leave the job or your company curtails the benefits under the group plan to cut costs.
Health Insurance: What You Need To Know During COVID
6 things to note before buying a Health Insurance
Things To Do After You Buy A Health Insurance
Is your employer’s Health insurance sufficient?
Health Insurance: Single Plan or a Family Floater Plan?

NOT PLANNING FOR CONTINGENCIES
Your long-term investments are not for meeting contingencies. Hence, all people, irrespective of age and employment status, must build a contingency fund. Ideally, your savings should guarantee you a lifestyle after retirement which is the same as you enjoyed in your working years. This involves high-level contingency planning as your income streams dry up as you retire.

NOT HAVING ENOUGH MONEY FOR EARLY RETIREMENT
Stress is nowadays burning out people at a young age, making them think of retiring early. We come across many people who want to advance their retirement age. But most of the time we advise them to delay the plan if they do not have enough funds to last their lifetime. Early retirement requires rigorous planning for meeting life's goals.

Compounding is a powerful tool (the longer the period, the more the money will grow). If you think you will start saving later when your income rises, you may not be able to save enough. Therefore, enlist a financial advisor, start immediately, evaluate the available savings and protection instruments, calculate the funds required and get down to executing the plan

NOT HAVING ADEQUATE INSURANCE
When a bread earner dies, the whole family suffers a setback. A life insurance policy can take care of the family's well-being in such a case. The question is, how much cover one should have?

The ideal figure is at least 10 times the annual salary. This will give the family a cushion of ten years to adjust to the new financial reality. For example, if your salary is Rs 12 lakh a year, the cover should be at least Rs 1.2 crore.
Another approach is calculating the human life value, that is, the present value of your future income. Don't forget to factor in liabilities such as home loans while doing the calculation.

Buy a term insurance policy as soon as you can. Buy online to save on premium. And do not forget to increase or decrease the cover as your liabilities change.

Conclusion

Retirement is the next great stage in your life, and it can be just as fulfilling and exciting as your younger years. It’s your opportunity to do what you want when you want, whether that means relaxing at home, traveling the world, or reinventing yourself in a new career.  No matter where you are on the retirement continuum, you have likely made mistakes along the way. By focusing on retirement planning now, you can feel more confident about fulfilling your vision, whatever it may be. If you don’t have enough saved, it is never too late to start planning.

In addition to avoiding the problem areas above, seek advice from a trusted financial advisor to help you stay—or get back—on track. We are SEBI registered investment advisors and can help you make sound investment decisions - you can reach out to us at iplan@wealthcafe.in, to help you make a financial plan for yourself. A lot of information you get daily may be totally irrelevant and can harm your financial interests, if you act on it without considering other factors.

RBI Retail Direct – Invest in Government Bonds online

Using the RBI Retail Direct platform, we can now invest in Government Bonds online. In the month of February 2021, RBI announced that it will allow retail investors to directly buy and sell Government Bonds online. Now through the RBI Retail Direct scheme, we can invest in Government Bonds online.

The launch date of the portal is not yet decided. According to the notification, “the date of commencement of the scheme will be announced at a later date”.

These are the securities which investors can invest: 

  1. Government of India Treasury Bills 
  2. Government of India dated securities 
  3. Sovereign Gold Bonds (SGB) 
  4. State Development Loans (SDLs)

ELIGIBILITY

Retail investors, as defined under the scheme, will be able to register under the Scheme and maintain an RDG Account, if they have the following:

i) Rupee savings bank account maintained in India;

ii) Permanent Account Number (PAN) issued by the Income Tax Department;

iii) Any OVD for KYC purpose;

iv) Valid email id; and

v) Registered mobile number.

Non-Resident retail investors eligible to invest in Government Securities under Foreign Exchange Management Act, 1999 will also be eligible under the scheme. The RDG account can be opened singly or jointly with another retail investor who meets the eligibility criteria.

SCOPE OF THE SCHEME

‘RBI Retail Direct’ is a comprehensive scheme that will provide the following facilities to retail investors in the government securities market through an online portal:

i) Open and maintain a ‘Retail Direct Gilt Account’ (RDG Account)

ii) Access to primary issuance of Government securities

iii) Access to NDS-OM

WHAT ARE THE SERVICES OFFERED?

The registered investors can opt for the following investment services: 

a. Financial Statement: The link provides transaction history and the balance position of securities holdings in the Retail Direct Gilt Account. All transaction alerts will be sent by e-mail or SMS. 

b. Provision for nominations: You can fill up and upload the nomination form in the appropriate format, which must be signed. A maximum of two nominations is allowed. 

c. Pledges and liens: Securities held in the RDG Account will be available for pledge/lien.

d. Transfers of Gifts Retail Direct: Investors will be able to give government securities to other Retail Direct Investors through an online platform. 

e. Grievance redressal: Any query or grievances related to the ‘Retail Direct’ Scheme can be raised on the portal which will be handled/resolved by Public Debt Office (PDO) Mumbai, RBI.

REGISTRATION:

Investors can register on the online portal by filling up the online form and using the OTP received on the registered mobile number and email ID to authenticate and submit the form. On successful registration, a ‘Retail Direct Gilt Account’ will be opened and details will be given through SMS/e-mail to access the online portal. The RDG account will be available for primary market participation as well as secondary market transactions on NDS-OM.

PROCEDURE

After registering on the online portal, retail investors will need to authenticate themselves by using OTP (one-time password) received on their registered mobile number and email address. They will need to submit the KYC document to open the RDG Account.

BUYING AND SELLING

During the bidding, the participation and allotment of securities will be as per the non-competitive bidding scheme of the RBI. The regulator has designed a non-competitive bidding scheme for non-institutional small buyers.

Once investors make the payments, RBI will credit the securities to their RDG Accounts.

To buy and sell securities in the secondary market, the procedure is similar to buying and selling of shares.

Before the start of trading hours or during the day, the investor must transfer funds to the designated account of CCIL (Clearing corporation of NDS-OM) online.

Based on actual transfer, a funding limit (buying limit) will be given to the investor for placing ‘buy’ orders. At the end of the trading session, any excess funds will be refunded.

FEES AND CHARGES

There are no fees charged for opening or maintaining the RDG account nor for Submitting bids in the primary auction. However, the registered investor will have to pay fees for payment gateway, etc. that are applicable.

However, do remember one thing that even though in such Government securities, default or downgrade may not be there, they are highly sensitive to the interest rate movement based on the time horizon of maturity of the bond.


Hence, investing in such Government securities does not mean they are safe. If you buy today and try to sell tomorrow (before maturity), then the risk of interest rate movement will be there. DO REMEMBER THAT INVESTING IN BANK FIXED DEPOSIT IS DIFFERENT THAN INVESTING IN GOVERNMENT BONDS. Understand the features and how they fluctuate and accordingly based on your need, you can buy. 

Where you do not wish to invest directly in government bonds as liquidity can be a concern here. Please note that RBI bonds are not as liquid as equity shares (where you are able to sell your equity shares anytime you'd like), there could be a situation where you do not find a buyer immediately, in that case, you must be ready to hold on to bonds for a longer duration. So where you want exposure to government bonds but not directly, mutual funds are the way forward for you.

How to retire with 5 cr on a salary of 1 lakh a month

We all have our aspirations and dreams for the golden years of our life. We want to have the freedom to do whatever we may want and hope to fulfill all the desires that were not fulfilled during the course of working life. It will only be possible if we have planned it well and enough funds are available to help us live our dreams. Thus, plan today for a beautiful post-retirement life.
You have been saving diligently for retirement. That's good. But in all likelihood, you have just a vague idea about what you want, not a concrete plan.

For example, many of you think that whatever you save during your working life will be sufficient for your sunset years. But have you accounted for the demon that goes by the name of inflation, which nibbles away the value of your money 24X7? Probably not. This means you will not save enough to be able to continue your present lifestyle in old age.
The first question that you may have when it comes to your retirement is

Where to invest for retirement?

When it comes to the accumulation of retirement corpus, people generally play safe and go for fixed interest-bearing risk-free instruments like fixed deposit, or PPF which at best give 8% return (in current market conditions, you are making only 7% there). But as retirement planning is for the longer term, one should take equity exposure to get a better return, which will help you accumulate a bigger corpus by retirement.
Equity can give you a 15% return on an average where you stay invested in it for a longer period of time to reduce the risk of volatility. A portion of the equity in your portfolio is a must. It is where wealth creation happens and it is what will also help you to achieve your corpus. We do not mean to suggest that you should invest 100% in Equity or 100% in Debt, you should invest in asset classes based on your risk profile and goals. Retirement being a long-term goal, one can invest some amount for it in Equity to enjoy the returns and manage the risk of it as well.

Let's understand How do you Invest - Basic Actionable Points?

  • Invest in Debt for Short term goals
  • Invest in a mix of Debt & Equity for long term goals (more than 3 years)
  • Now, this mix of debt and equity is determined based on your risk profile. You can take your risk profile test here - Risk Calculator

This test will help you determine how much risk you are comfortable taking and guide you to invest based on that, rather than investing all your money in equity and having sleepless nights.
You can read more about this here: How should you invest


For the purpose of understanding this working and your goal to achieve a corpus of 5 crores with an income of 1 lakh, let's assume that our investor’s profile is a GROWTH profile and he is going to invest in equity and debt. His Debt-Equity Mix will be 30% debt and 70% equity.

How much you need to invest every month to accumulate Rs 5 crore

Now let's come to the main question - HOW MUCH?
The amount you need to invest to accumulate a corpus of Rs 5 crore will depend on your current age and the age that you want to retire. (i.e. your time to retire)
For example, (where your risk profile is a growth profile) and your current age is 25 years and you want to retire at the age of 55 years then you need to save Rs 11,694 every month for the next 30 years to accumulate Rs 5 crore. This is assuming an annual return of 12.90% (which is derived based on the asset allocation of your risk profile of GROWTH).


The required amount will go up to Rs 13,335 if you start one year later at the age of 26. Similarly, if you delay it by five more years, then you will be required to invest Rs 22,656 every month to accumulate the same amount. The required amount increases drastically with a delay in investment as the effect of compounding reduces.


Here is an illustration of how much you need to save every month to accumulate Rs 5 crore by retirement assuming that your investment grows at an annual rate of 12.90%.

However, if you are young and starting out, it is important to know that you do not need a lot of investments to reach 5 crores - just INR 11,000 is good to begin with, which is not a lot of money - given the time and funds involved. It definitely seems like an achievable goal. 

Worth mentioning here is that you also need to create an emergency fund and your insurance as well as medi claim along with your regular investment for retirement so that your retirement corpus remains untouched in case of emergencies like job loss, hospitalization, or any pandemic that we are witnessing now, which can create potential risk to employment. Also, you may have many goals that may come and go as your life goes o, but your retirement will always be THE MOST important goal.

Do not forget that 'Retirement is that one goal you will never get a loan for, you have to plan for it all by yourself'

[mc4wp_form id="2150"]

WCafe Financial Services Pvt Ltd (formerly known as Wealth Cafe Financial Services Pvt Ltd) is a AMFI registered ARN holder with ARN-78274.

WCafe Financial Services Pvt Ltd (formerly known as Wealth Cafe Financial Services Pvt Ltd) is a SEBI registered Authorised Person (sub broker) of Sharekhan Limited with NSE Regn AP2069583763 and BSE Regn AP01074801170742.

Copyright 2010-20 Wealth Café ©  All Rights Reserved